Gold pauses after PPI, but real yields leave a tougher weekend test
Saturday’s Gold Brief reviews 13 November: a near-flat gold settlement, firmer real yields and the evidence needed before calling the pause a recovery.
New York session reviewed: 2026-11-13
Published
Editorial cutoff · Gabriel Nicolaev — CyGuru
The five-question brief
What happened?
The last completed New York session was Friday, 13 November 2026. Treasury’s ten-year nominal par yield was 5.15% and its ten-year real par yield 2.91%, both five basis points above 12 November. Saturday is the Dubai publication date, not a new market session.
What explains it?
The article below separates verified releases from conditional interpretations. A headline alone does not establish the cause of a price move.
What is still missing?
Final spot close, verified intraday OHLC and a directly obtained exchange settlement file were unavailable. The chart contains two reported futures settlements only. Weekly spot return endpoints, synchronized cross-market attribution, broker fills and signal outcomes are unverified.
What could change the reading?
Contradictory observations over matching timestamps, revised source data or failed follow-through can weaken an interpretation. An explanation must be reconsidered when its required evidence is absent.
What will I watch?
At the next market reopening, compare gold, the same dollar index and yields over matching intervals. A sustained recovery alongside easing real yields would offer different evidence from an isolated opening price jump.
The last completed New York session was Friday, 13 November 2026. Treasury’s ten-year nominal par yield was 5.15% and its ten-year real par yield 2.91%, both five basis points above 12 November. Saturday is the Dubai publication date, not a new market session.
A pause is an observation; a recovery is a hypothesis
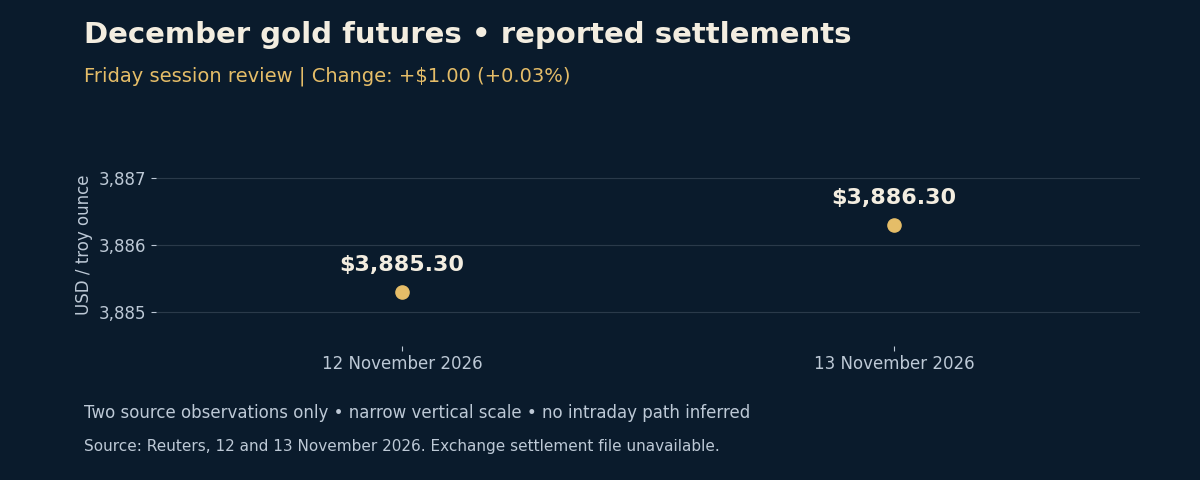
Reuters reported December gold settling at $3,886.30 on Friday, against Thursday’s $3,885.30: a calculated $1.00, or 0.03%, increase. Its spot observation was $3,879.71, up 0.1%, at 19:05 UTC / 23:05 Dubai. Neither quote supplies a final spot close. The small settlement change describes the endpoint of one session. It cannot establish that selling pressure has been exhausted or that a durable support level has formed. That distinction is the central preparation question for the next session.
The inflation release needs more than one comparison
BLS released October PPI on Friday at 13:30 UTC / 17:30 Dubai. Seasonally adjusted final-demand prices rose 0.3% monthly, after a revised 1.4% in September; the unadjusted annual increase was 6.5%. Goods rose 0.5% and services 0.2%. Excluding foods, energy and trade services, prices rose 0.5% monthly and 4.9% annually. These measures have different baskets. My interpretation: a slower headline monthly increase does not by itself establish broad disinflation. Nor does one producer-price release map mechanically into consumer inflation or the next policy decision.
The rate backdrop did not ease at the daily horizon
Between 12 and 13 November, Treasury’s two-year nominal par yield rose from 4.86% to 4.88%. The ten-year nominal yield increased from 5.10% to 5.15%, while the ten-year real yield moved from 2.86% to 2.91%. The simple nominal-minus-real spread consequently remained 2.24 percentage points. That subtraction is a rough comparison of two published par curves, not a clean inflation forecast or a traded breakeven quote. The practical inference is narrower: the nominal rise was accompanied by an equal rise in the real reference, so describing Friday only as an inflation-expectations story would omit relevant evidence.
Keep the dollar measures and clocks separate
Reuters’ 13 November currency report gave DXY at 103.34, up 0.1%; its exact quote minute was unspecified. This supports a dated dollar observation, not a synchronized causal test against gold. Separately, the Federal Reserve’s broad dollar index on FRED still showed 121.8803 for 6 November, updated on 9 November at 21:16 UTC. Gold Today retains that older date. These indices have different construction and scales; substituting one for the other would create a false comparison. Refreshing the page does not turn the lagged observation into a Friday reading.
My interpretation: resilience under pressure, not proof of a turn
A nearly unchanged gold settlement alongside higher real yields is compatible with some resilience. It does not identify the buyers, quantify safe-haven demand or demonstrate that the usual opportunity-cost channel has stopped mattering. Those claims require evidence that this edition does not have. A competing explanation is simply that one session’s net move concealed opposing flows. Without matched intraday observations, neither explanation earns priority from an attractive chart alone. The useful conclusion is to preserve both possibilities and specify what would distinguish them next.
A weekend observation plan for the next session
Begin with the instrument and clock: the same futures delivery month for settlement comparisons, a separately named spot provider, one defined dollar measure, and nominal and real yields with their own dates. Record the first tradable observations after reopening before choosing a narrative. If gold advances while the dollar and real yields also advance, investigate additional demand rather than forcing a simple inverse relationship. If real yields and the dollar ease but gold cannot retain gains, that would weaken the claim that macro relief alone is sufficient. These are research conditions, not entry instructions or predicted outcomes.
What the chart can and cannot establish
The two dots above retain the source-reported settlements and session dates. The narrow price scale makes the one-dollar difference visible and is explicitly labeled; it must not be read as a large return. No verified intraday chart is available for this edition, and no candles have been invented. There is also no certified weekly spot return here because matched weekly endpoints were not obtained. Use the next official calendar updates to prepare new event baselines; this Saturday note does not announce a Saturday gold session. Market widgets retain their provider timing, while this archived analysis remains fixed.
Sources and observation times
- Reuters · Anjana Anil · 13 November dispatch (initial stamp 03:43 UTC; updated body includes 19:05 UTC spot and December settlement) ↗
- Reuters · 12 November dispatch · prior December-contract settlement; settlement publication minute unspecified ↗
- BLS · October PPI · released 13 November 2026 at 08:30 ET / 13:30 UTC; linked rolling release checked at cutoff ↗
- U.S. Treasury · 12–13 November nominal daily par curves; exact publication hour unavailable ↗
- U.S. Treasury · 12–13 November real daily par curves; exact publication hour unavailable ↗
- Reuters · 13 November currency dispatch (initial stamp 01:58 UTC); DXY quote minute unspecified ↗
- Federal Reserve via FRED · broad dollar index · 6 November observation, updated 9 November at 21:16 UTC ↗
Sources checked for this edition at the editorial cutoff above. Provider observation times remain separate from publication time. Linked statistical pages may later display revised data.
Continue the study
Read inflation releases with precision →
Research Lab: study the price record →
Educational editorial analysis, not a trade recommendation. This archived edition does not update with later announcements.